Minimum Competency Code: 4 duties and what to keep on file
The minimum competency code asks four things of a firm and its advisers: qualification, CPD, record keeping and firm responsibility. We go through each duty, with the Central Bank's wording and dates, and what a small practice needs on file to show it was met.
 James Brooks · Founder, Kaitel · 7 min read
The minimum competency code asks four things of a firm and its advisers. Each adviser holds the qualification for their function and keeps up their CPD, ethics included. The firm keeps a register of accredited persons, reviews it all each year and holds the records, so it can prove each duty.
What you'll learn
- The Code sets standards for people, but the Minimum Competency Regulations put the duties on the firm, so the firm has to prove them.
- In 2024 the Central Bank found that smaller independent intermediaries struggled to evidence the Code, and it blamed poor record keeping.
- Each of the four duties has a matching record, so a practice can check its own file against the list.
- The register of accredited persons is the document the Central Bank found falling short on format, clarity and detail.
- Since 28 July 2026 the consumer definition and the annual review wording have changed, so an older summary is out of date.
The Central Bank found small firms could not prove the minimum competency code was met
The Code sets standards for people. The Regulations put the duties on the firm.
Both took effect in 2018, and the Regulations place their obligations on regulated firms.
The Central Bank then reviewed how retail intermediaries were doing against this Code and the Consumer Protection Code. Its industry letter of 29 May 2024 found the risks and breaches “far greater in smaller, independent Retail Intermediaries”.
Here is what that looked like. Asked to show the Code was met, several intermediaries could not. The letter says they were “unable to provide adequate evidence and/or documentation”.
Take a small practice in Galway, made up for this post. Everyone is qualified, but one certificate sits in an old email and nobody has reviewed the register in years. The qualifications are real. The file cannot show them.
The Central Bank put the cause down to the file.
“...inadequate or ineffective internal processes and controls, and general poor record keeping and file management.” Central Bank industry letter, 29 May 2024
The consumer definition has also widened since July. The amending regulations lift the turnover threshold for incorporated bodies to €5 million.
William Fry notes that this brings more companies into scope. Older summaries still show the old figure.
We counted 2,689 firms on the Central Bank's intermediary registers this month, and those with accredited persons owe the duties below.
Duty one: each person holds the qualification, and the firm can show it
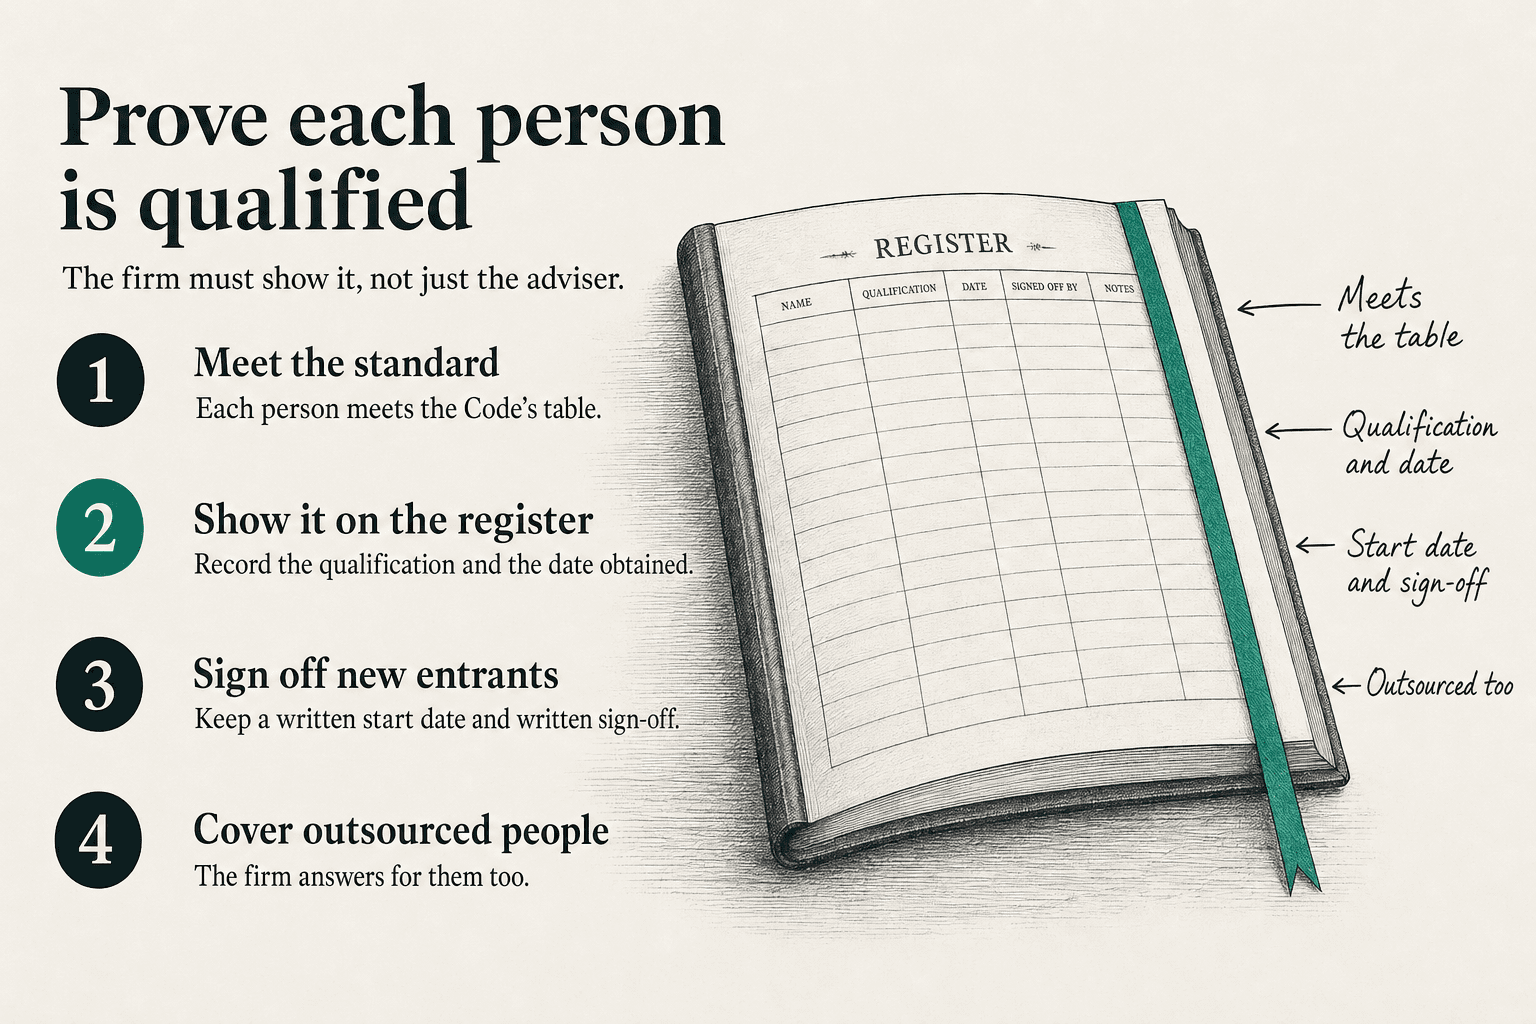
The first duty is qualification, and it sits with the firm as well as the adviser.
The Code says a person is not taken to comply unless they meet the standards in its table. Which qualifications count is covered in a separate post on the qualification list.
The firm's part is in the Regulations. Under Regulation 4, the firm must make sure each person has the skills their role needs, gained through experience or training at work.
The firm must also ensure that people doing outsourced work for it meet the standards, as the reworded Regulation 3 sets out.
A new entrant's work needs written sign-off. Until they qualify, a person who meets the Code's standard for qualified persons must check and approve their documentation in writing.
The firm also keeps a written record of the date the new entrant started. Regulation 10 asks for more than that, so read it in full.
The lists in this post are our reading of the rules, not a list the Central Bank has published.
What to keep for this duty:
- The qualification and the date it was obtained, on the register.
- For a new entrant, the written start date and the written sign-off.
- The same records for outsourced people the firm is responsible for.
Duty two: the minimum competency code asks for 15 CPD hours a year, one on ethics
The second duty is CPD, and the firm has to make sure it happens.
The Central Bank's Questions and Answers describe the standard as at least 15 hours of CPD each year, with at least one hour on ethics. The CPD overall must also cover a range of the competencies the person's activities need.
A recognised qualification provider or a professional body must accredit every hour. So the log should record who accredited each one.
The firm's own duty is in Regulation 14. It must “establish, maintain and adhere to procedures” so each person meets the CPD requirements on an ongoing basis.
Regulation 15 lists the records to keep: monitoring of CPD compliance, proof of compliance, breaches, and any pro-rata adjustments. Its last item, on pro-rata adjustments, has more detail than we quote.
What to keep for this duty:
- A CPD log for each person, showing hours, topic and who accredited them.
- The firm's written CPD procedures.
- The firm's monitoring records and any breach records.
Duty three: the register of accredited persons is where the Central Bank found gaps
The third duty is record keeping, and the register is the central record.
Under Regulation 7, each entry records:
- The accredited person's name.
- Their qualification, or grandfathered, transitional, new entrant or prescribed script status.
- The relevant function and related retail financial product.
- The date they obtained the qualification and experience.
- For a new entrant, the start date and the qualification being pursued.
Each branch office must have a register of all accredited persons working in that branch.
The register is a live record. A person whose professional designation is removed or suspended for failing CPD comes off it, and goes back on promptly once they are fully compliant.
The same 2024 letter found registers reviewed to varying standards and at varying frequencies. In certain cases they fell short on format, clarity and detail, and it was not clear they had been kept up to date. It named regular scheduled reviews as good practice.
Nothing we read says what evidence of a qualification to hold. Our suggestion is to keep the certificate beside the register entry.
What to keep for this duty:
- One register for each branch, with every field complete.
- A dated note each time someone reviews the register.
- Updates whenever a person joins, qualifies, leaves or loses a designation.
Duty four: under the minimum competency code the firm answers for the review and the records
The firm answers for what an adviser cannot do alone. It ensures each person meets the standards, keeps the register, runs CPD procedures, reviews annually and keeps the records. The adviser's own duties are the qualification and the CPD hours.
The reworded Regulation 13 sets the annual review. The firm carries out an internal review of its employees' qualifications, including whether each recognised qualification suits the function.
It also reviews their development and experience needs, taking account of regulatory developments and new products.
Records that show a person's compliance must be kept for at least 6 years after that person stops performing the function for the firm.
The Central Bank put the responsibility on every firm to be able to “demonstrate its compliance with all relevant regulatory requirements on a continuous basis”.
It also asked firms to document their own review of these arrangements, and said that document must be available in future engagements. The deadline it set has passed.
What to keep for this duty:
- A written, dated annual review of qualifications and development needs.
- The CPD procedures and the register review notes.
- Every record, held for the full retention period.
Check one adviser's file against all four duties
Before you rely on your minimum competency file, check:
- Every person giving advice has an entry on the register for their branch, with function, qualification and date obtained.
- Each new entrant has a written start date and written sign-off on their work until they qualify.
- Each person's CPD log shows 15 hours this year, at least one on ethics, with who accredited each hour.
- Someone reviews the register on a set schedule, and the review is written down and dated.
- The annual review of qualifications and development needs is written down and dated, and covers the points in the 28 July 2026 wording.
- Records are kept for 6 years after a person stops performing the function, including outsourced people the firm is responsible for.
Pick one adviser in the practice and see whether the file alone shows each of the four duties. Whatever is missing is the practice's to-do list.
We are building Kaitel with Irish advice practices, around their own documents, processes and compliance, and you can join the waitlist so we can keep you posted.
Sources
- Central Bank of Ireland, Minimum Competency Code and Minimum Competency Regulations 2017, undated page
- Central Bank of Ireland, Minimum Competency Code 2017, 2017
- Irish Statute Book, S.I. No. 391/2017, Minimum Competency Regulations 2017, 1 September 2017
- Irish Statute Book, S.I. No. 295/2026, Minimum Competency (Amendment) Regulations 2026, 25 June 2026
- Central Bank of Ireland, Industry letter: Thematic Review of Compliance with the Minimum Competency Code and Consumer Protection Code, 29 May 2024
- Central Bank of Ireland, Minimum Competency Code 2017 and Minimum Competency Regulations 2017, Questions and Answers, updated June 2026
- William Fry, Central Bank Updates MCC Requirements, 9 July 2026
- Kaitel count of firms on the Central Bank's intermediary registers, 23 October 2026
The meeting ends. Kai starts.
Founding cohort · Irish advice firms
Not ready yet? Join the waitlist
James Brooks is the founder of Kaitel. An investment analyst turned founder, he works directly with practising Irish advice firms on the paperwork around the client meeting: fact finds, file notes, suitability letters and follow-ups.